Innovation
How Programmable Payments Work With Tokenized Deposits
Programmable payments attach rules to money, and tokenized deposits give those rules something safe to move. Here is how the two layers fit together.
October 12, 2026
Programmable payments attach rules to money, and tokenized deposits give those rules something safe to move. Here is how the two layers fit together.
Cards and wallet apps are layers of the same system, not rivals. How each works, where each shines, and how to pick the right one at the counter.
A wrong charge is not the end of the story. How chargebacks work, the rights behind them, and the steps that give your dispute its best chance.
A payments hub gives merchants one integration and many payment providers. This guide explains the architecture layer by layer, from gateway to settlement.
Recurring payments fade into the background until a statement surprises you. Here is a simple routine to track, rate, and manage every subscription.
A single card payment crosses at least four companies between checkout click and settled funds. Here is the route, and where the fees sit along it.
A step-by-step guide to opening a first bank account, including what banks check, what second-chance options exist, and what to do if you have been declined…
Pennsylvania's largest digital-first credit union says a multi-year rebuild of its member experience will start with joint planning now underway.
Implementation, measured impact and evidence usually outrank novelty, which is why polished pitches with no traction lose to quieter products that work.
Experimentation on a tight budget is a process problem, not a money problem — and the process is buildable.
A technical analyst puts a $82,900–$83,000 support zone at the center of the October outlook; the levels are sourced, but the method deserves a second look.
A chargeback reverses a card sale at the issuer's hand before the merchant hears about it, and the merchant's only recourse is evidence, not argument.
A working method for separating what a market story proves from what its headline implies.
The acquiring bank routes the authorization, absorbs the merchant's risk, batches the day's sales, and funds the merchant's account — usually minus fees.
A chargeback pulls funds back from a merchant's account before any human at the business sees a complaint, and the clock the merchant is racing starts the…
The FDIC put the national average savings rate at 0.46 percent in February 2024, while the largest online banks kept paying above 4 percent APY.
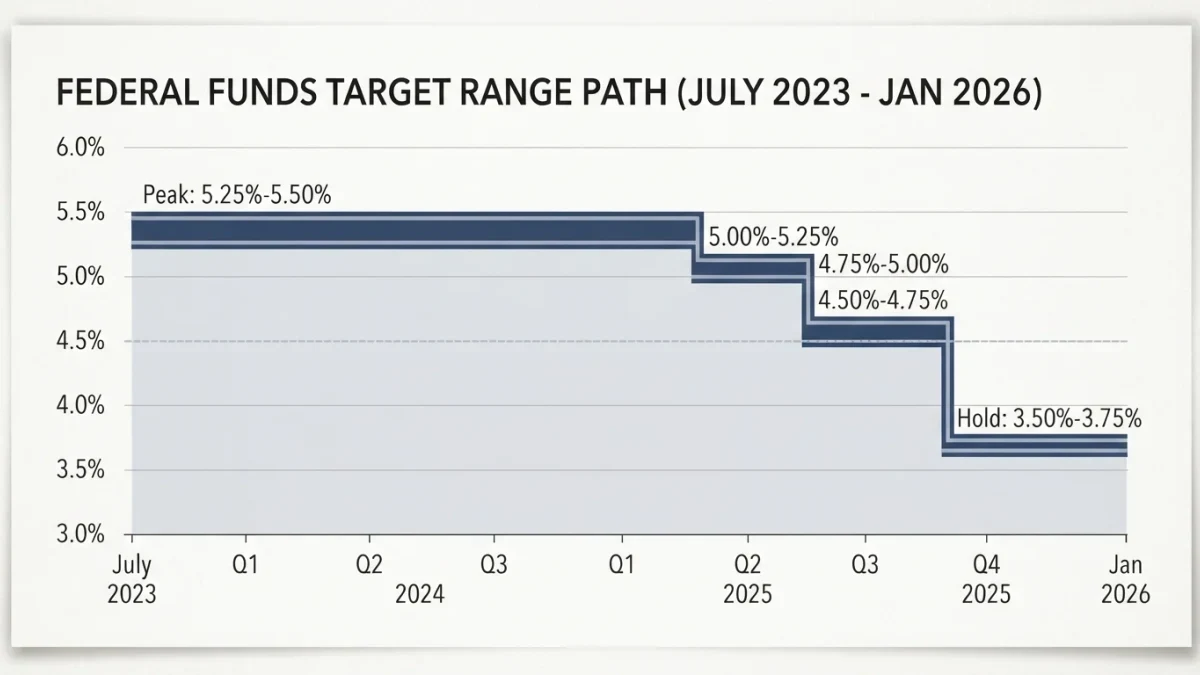
The FOMC kept the federal funds target range at 3.50%-3.75% on January 28, 2026, with governors Stephen Miran and Christopher Waller dissenting for a…
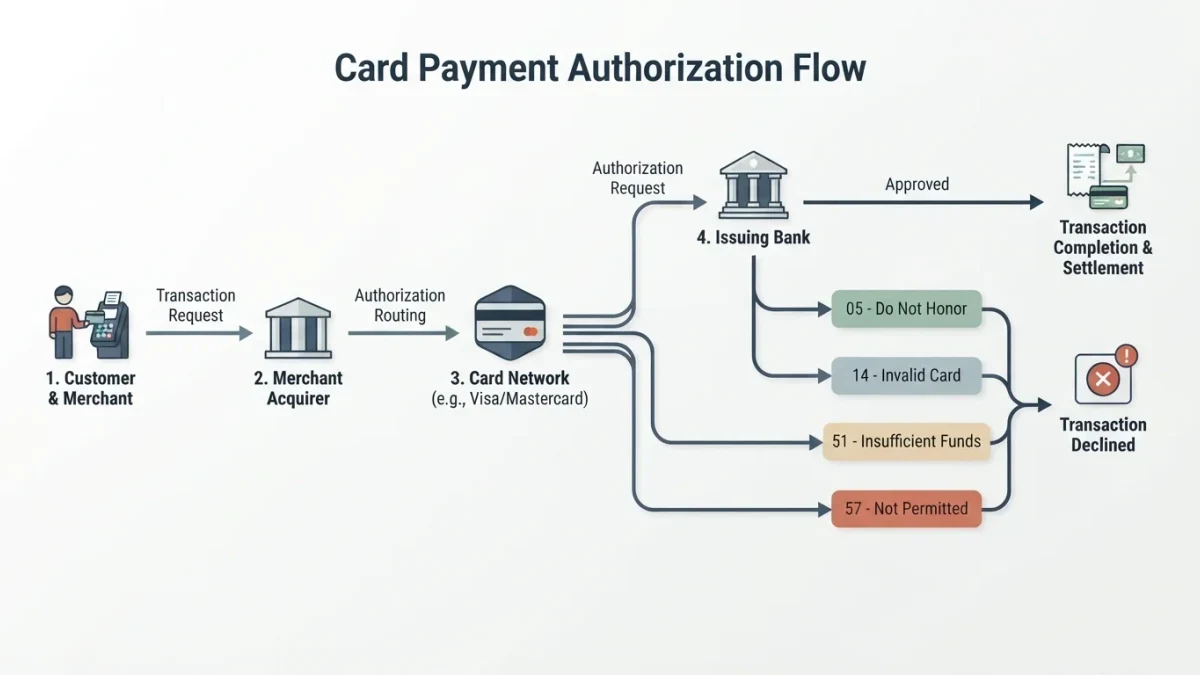
Issuer response codes such as 05, 14, 51 and 57 each carry a different operational instruction for merchants, from retry timing to card-on-file hygiene.